4-Point Inspection Repairs: What Homeowners Need to Fix
A failed 4-point inspection can stall your insurance, sale, or refinance. Here is what fails most often in Tampa and how to fix it quickly.
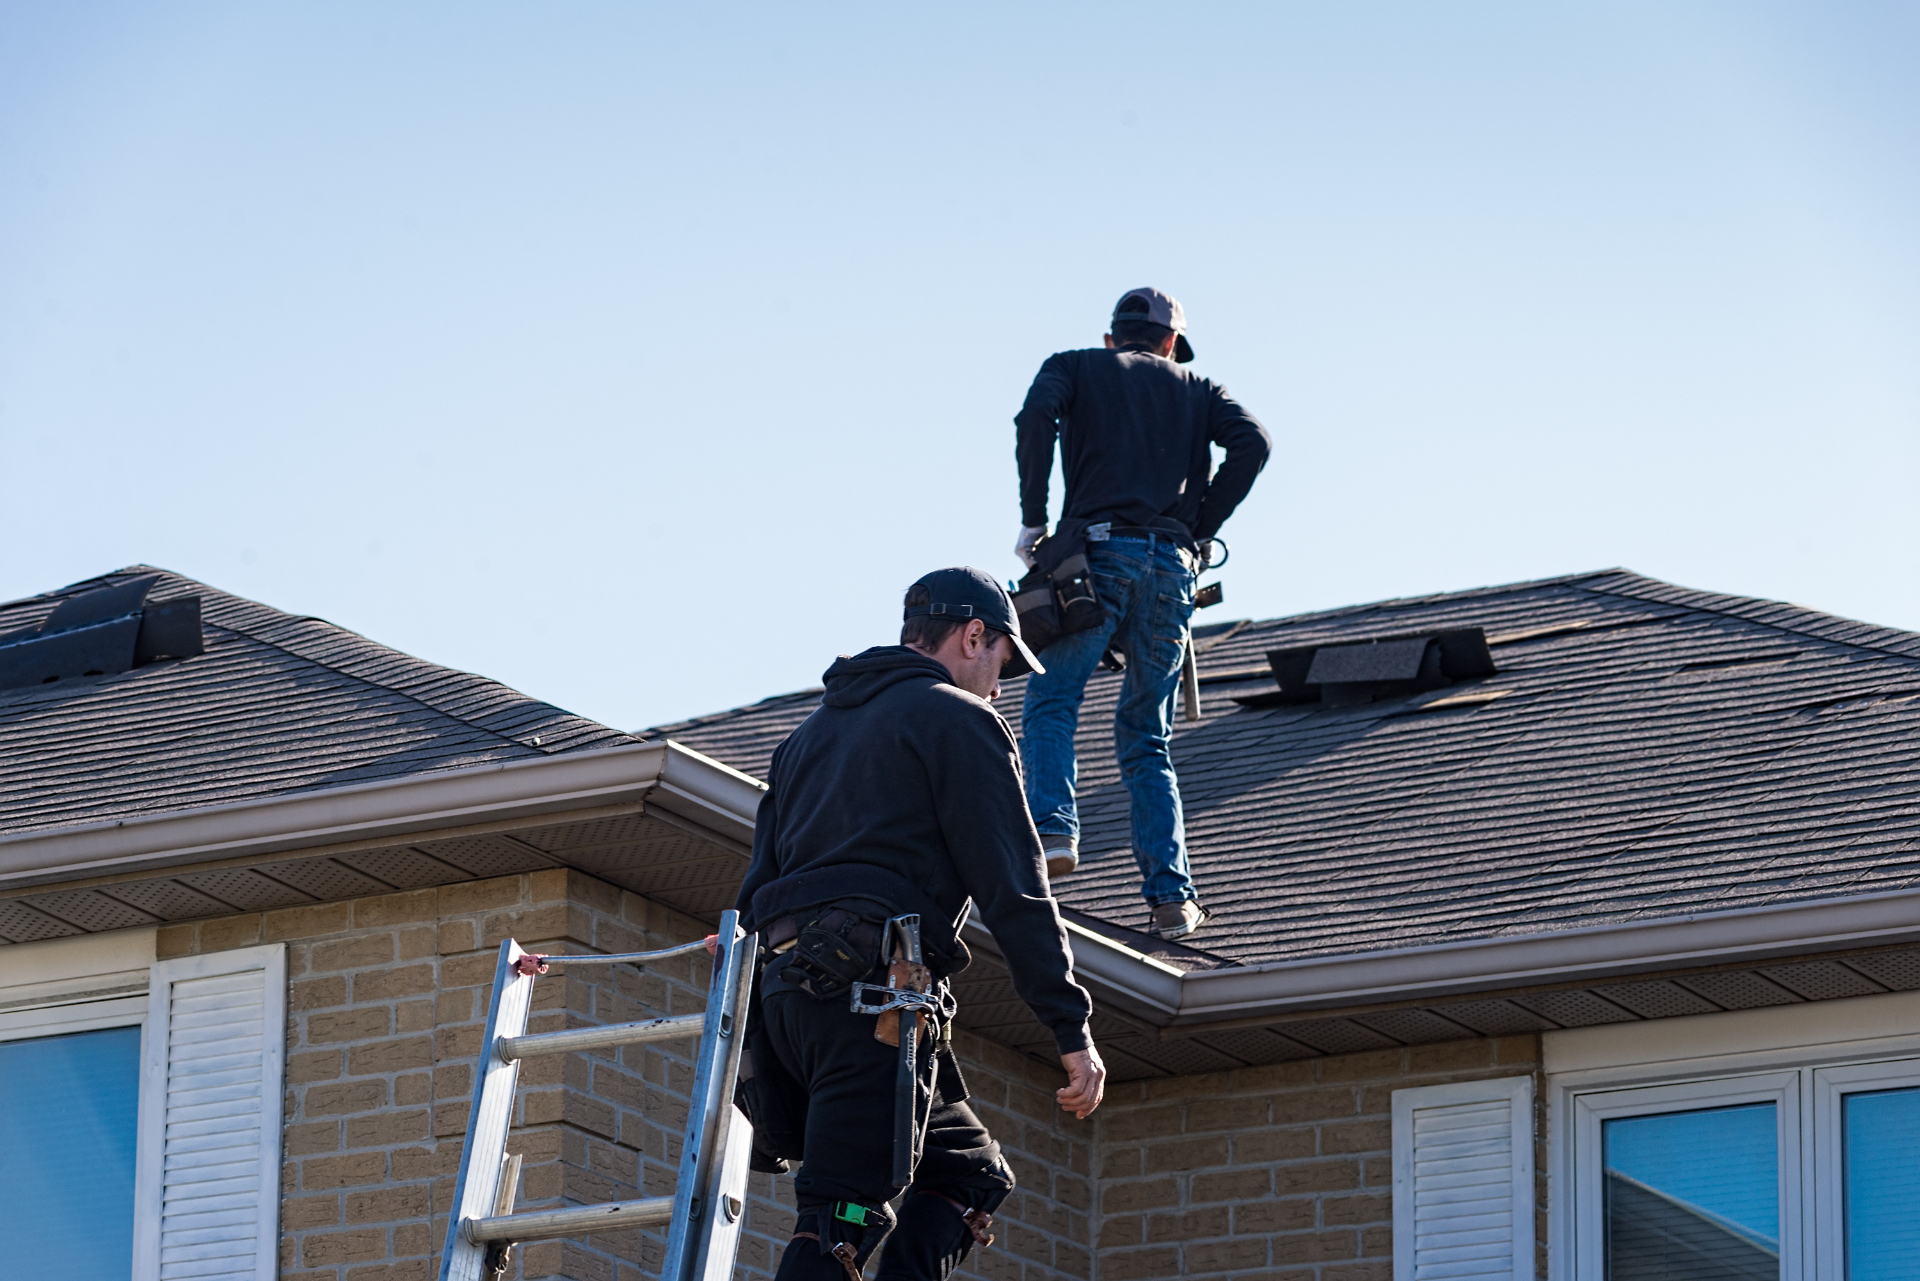
If your insurance carrier or buyer just requested a 4-point inspection, you are not alone. Florida insurers rely on this report to decide whether to write a policy at all. A single failed item can stall coverage, a sale, or a refinance. This guide explains what 4-point inspections cover, what fails most often in Tampa, and what repairs you will need to complete to move forward.
What Is a 4-Point Inspection?
A 4-point inspection evaluates the four major systems most likely to drive an insurance claim: roof, electrical, plumbing, and HVAC. It is shorter than a full home inspection and is required by most Florida carriers on homes 20 years and older, with many carriers now requesting it earlier. Insurers use it to confirm each system is in serviceable condition with reasonable remaining life.
Common Issues Found in 4-Point Inspections
- Roofing. Age beyond carrier limits, missing shingles, lifted flashing, soft decking, ponding water, and visible leaks.
- Electrical. Federal Pacific or Zinsco panels, double tapped breakers, knob and tube remnants, aluminum branch wiring, and missing GFCI or AFCI protection.
- Plumbing. Polybutylene supply lines, active leaks, corroded valves, and water heaters past expected life.
- HVAC. Systems past 15 years, no service records, condensate leaks, and improperly sealed plenums.
Most Common Roof Related Failures
Roof items drive the majority of 4-point failures in Tampa Bay.
- Age. Asphalt shingle roofs older than 15 years often fail eligibility outright.
- Active leaks or interior staining. Any moisture intrusion is a hard fail.
- Visible damage. Missing or curling shingles, cracked tiles, exposed fasteners, and damaged ridge vents.
- Improper installation. Short overhangs, wrong fastener pattern, missing drip edge, and unpermitted prior work.
Tampa Specific Insurance Challenges
- Stricter underwriting. Florida carriers continue to tighten roof age and condition rules and decline more applications outright.
- Storm risk. Tampa Bay sits in a 150 mph design wind zone under the 7th Edition Florida Building Code, so any roof weakness reads as elevated claim risk.
- Older housing stock. Many South Tampa, Seminole Heights, and inland Hillsborough homes have aging electrical and plumbing alongside the roof, creating multi system findings on a single report.
What an Authoritative Source Says
The Federal Emergency Management Agency (FEMA) Building Science library documents how proper installation and routine maintenance of roof coverings, fasteners, and flashings significantly reduce wind and water damage during named storms. Insurers underwrite from the same principle. A maintained, code compliant roof is a measurably lower risk, and that is exactly what the 4-point report is designed to confirm.
What Repairs Are Typically Required
- Roof. Replace damaged shingles or tiles, re seal penetrations, replace cracked vent boots, repair or replace flashing, and address decking damage. Carriers may require a full Tampa roof replacement when age or condition disqualify repair.
- Electrical. Replace outdated panels, eliminate double taps, add GFCI or AFCI protection where required.
- Plumbing. Replace polybutylene supply lines, repair active leaks, and replace failed water heaters.
- HVAC. Service records, condensate repairs, and replacement of systems past life.
Timeline. Most carriers allow 30 to 60 days from binding to complete required repairs. Roof work in Tampa typically requires permits through Hillsborough or Pinellas county, so plan for inspection and re inspection time on top of installation.
How to Prioritize Repairs
- Address any active leak or safety item first.
- Tackle items that block insurance binding before cosmetic or comfort items.
- Document every repair with invoices and photos for the carrier and any future buyer.
- Order a follow up Tampa roof inspection to confirm the corrected report is acceptable.
Replacement is the right call when the roof is past insurable age, has widespread damage, or fails wind mitigation. For homes in Lutz, a roof inspection ahead of policy renewal often surfaces the items insurers will flag before the report is filed.
Schedule an Inspection or Repair Quote
Weathershield Construction Services performs roof inspections and 4-point related repairs across Tampa Bay. We document the work in a format your carrier will accept.
Schedule an inspection or request a repair quote to get your home back to insurable condition.
Frequently Asked Questions
Explore Our Services, Guides & Tampa Bay Locations
We provide roofing, impact windows, siding, and storm restoration throughout Tampa Bay. Explore our services, homeowner guides, and local service areas below.
Exterior Services
Licensed exterior solutions built for Florida's climate and building codes.
Homeowner Guides
In-depth resources on materials, costs, and insurance for Florida homeowners.
Tampa Bay Service Areas
Serving homeowners across Hillsborough and Pinellas counties.
More Articles for Tampa Homeowners
What Realtors Look for in a Roof Inspection in Tampa
Roof inspection reports drive Tampa real estate transactions. Here is what realtors look for, what kills deals, and how to prepare your roof before listing.
May 13, 2026
How Roof Condition Affects Home Value in Tampa
Roof condition is one of the first things Tampa buyers, inspectors, and insurers evaluate. Here is how it shapes your sale price and what to do before you list.
May 11, 2026
Top Questions to Ask a Roofing Contractor in Tampa
A practical question-by-question guide to vetting any Tampa roofing contractor before you sign a contract.
May 8, 2026